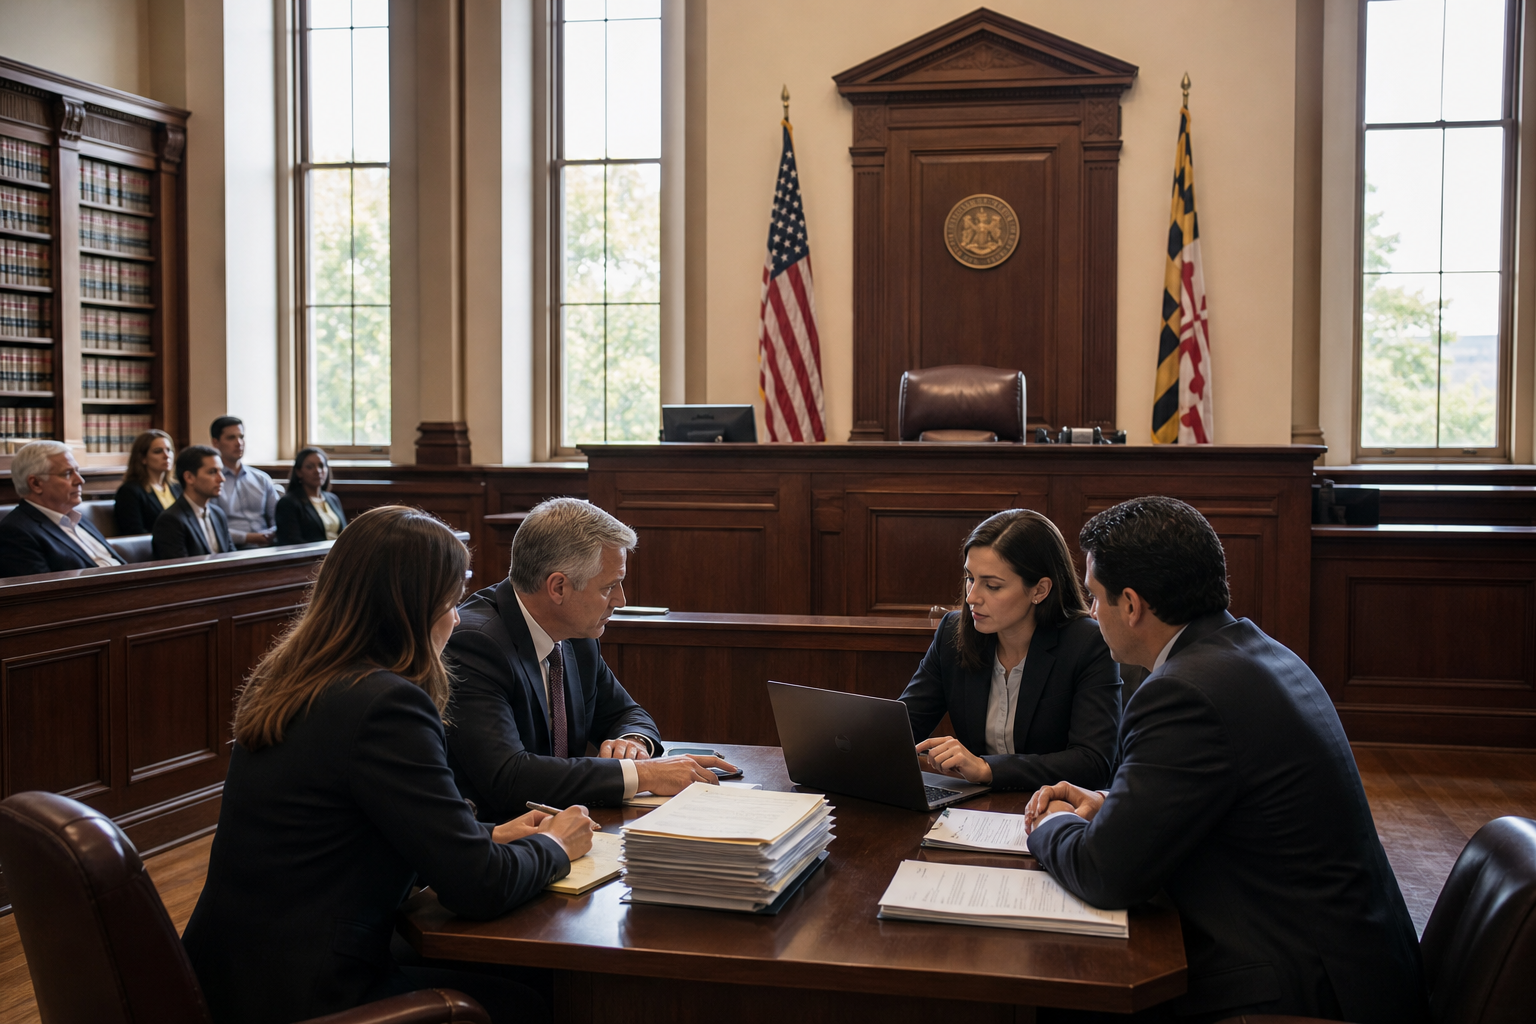
Key details: The Maryland Tax Court struck down the state’s digital advertising gross revenues tax in Apple Inc. v. Comptroller, No. 23-DA-00-0456 (2026), concluding that the tax violated the Internet Tax Freedom Act and constitutional protections. The decision may create refund opportunities for affected businesses, but the possibility of an appeal means companies should review their filings, preserve documentation, and evaluate next steps with their tax advisors.
How Maryland’s Digital Advertising Tax Worked
Maryland was the first state to implement a tax specifically on digital advertising services. The tax applied to businesses with at least $100 million in worldwide annual gross revenue and at least $1 million in annual gross revenue from digital advertising services in Maryland. It applied to tax years beginning after December 31, 2020.
- 2.5% for businesses with worldwide annual gross revenue of $100 million through $1 billion;
- 5% for businesses with worldwide annual gross revenue above $1 billion through $5 billion;
- 7.5% for businesses with worldwide annual gross revenue above $5 billion through $15 billion; and
- 10% for businesses with worldwide annual gross revenue above $15 billion.
Why the Maryland Tax Court Rejected the Tax
The court focused on two central issues. First, the tax rate was determined by a company’s worldwide revenue rather than solely by its Maryland activity. The court agreed with the taxpayers that this structure burdened interstate commerce and raised concerns under the Dormant Commerce Clause and the Due Process Clause.
Second, the court found that digital and traditional advertising were sufficiently similar that taxing only digital advertising discriminated against electronic commerce in violation of the Internet Tax Freedom Act. Together, those findings led the court to invalidate the tax and order refunds, with interest, for taxes paid under the regime.
What the Ruling Could Mean for Affected Businesses
- Potential refund claims: Businesses that paid the Maryland digital advertising tax should determine whether they may be eligible for a refund and related interest.
- Material financial impact: Because the tax rate reached 10%, potential refund amounts may be significant for some taxpayers.
- Continued uncertainty: Maryland may appeal the decision. Any appeal, stay, or later ruling could affect timing, procedures, and the ultimate availability of relief.
- Broader state-tax implications: Other states considering taxes on digital activity may reassess how those proposals are structured in light of the court’s analysis.
Practical Steps to Take Now
Businesses that paid, accrued, or evaluated exposure to Maryland’s digital advertising tax should consider the following actions:
- Confirm the tax periods and amounts paid.
- Gather returns, payment confirmations, revenue-sourcing workpapers, and correspondence with the Maryland Comptroller.
- Review refund procedures and applicable deadlines with a qualified tax advisor.
- Assess the accounting and financial-statement implications of a potential refund or ongoing dispute.
- Monitor the case for appeals, stays, or administrative guidance before relying on the decision as final.
How Ryan & Wetmore Can Help
Digital advertising tax developments can affect refund opportunities, state tax exposure, documentation requirements, and financial reporting. Ryan & Wetmore’s state and local tax professionals can help businesses review prior filings, evaluate refund considerations, and monitor how this litigation may affect their broader multistate tax strategy. Contact Ryan & Wetmore to discuss how the Maryland digital advertising tax ruling may affect your business and the steps you should consider now.
This article is intended for general informational purposes and does not constitute tax or legal advice. The decision, refund procedures, deadlines, and appellate status should be confirmed by the appropriate subject-matter reviewer before publication or action.
Today’s Thought Leaders
About Peter Ryan
Partner, Co-founder, & CPA
Peter T. Ryan co-founded Ryan & Wetmore in 1988 with business partner Michael J. Wetmore. Peter provides clients with the best strategies for success. His expertise extends across various industries. Peter obtained a Master of Business Administration in Finance from the University of Baltimore and a Bachelor of Arts in Accounting from the Catholic University of America.